运动员仓库控股公司2026年季度报告
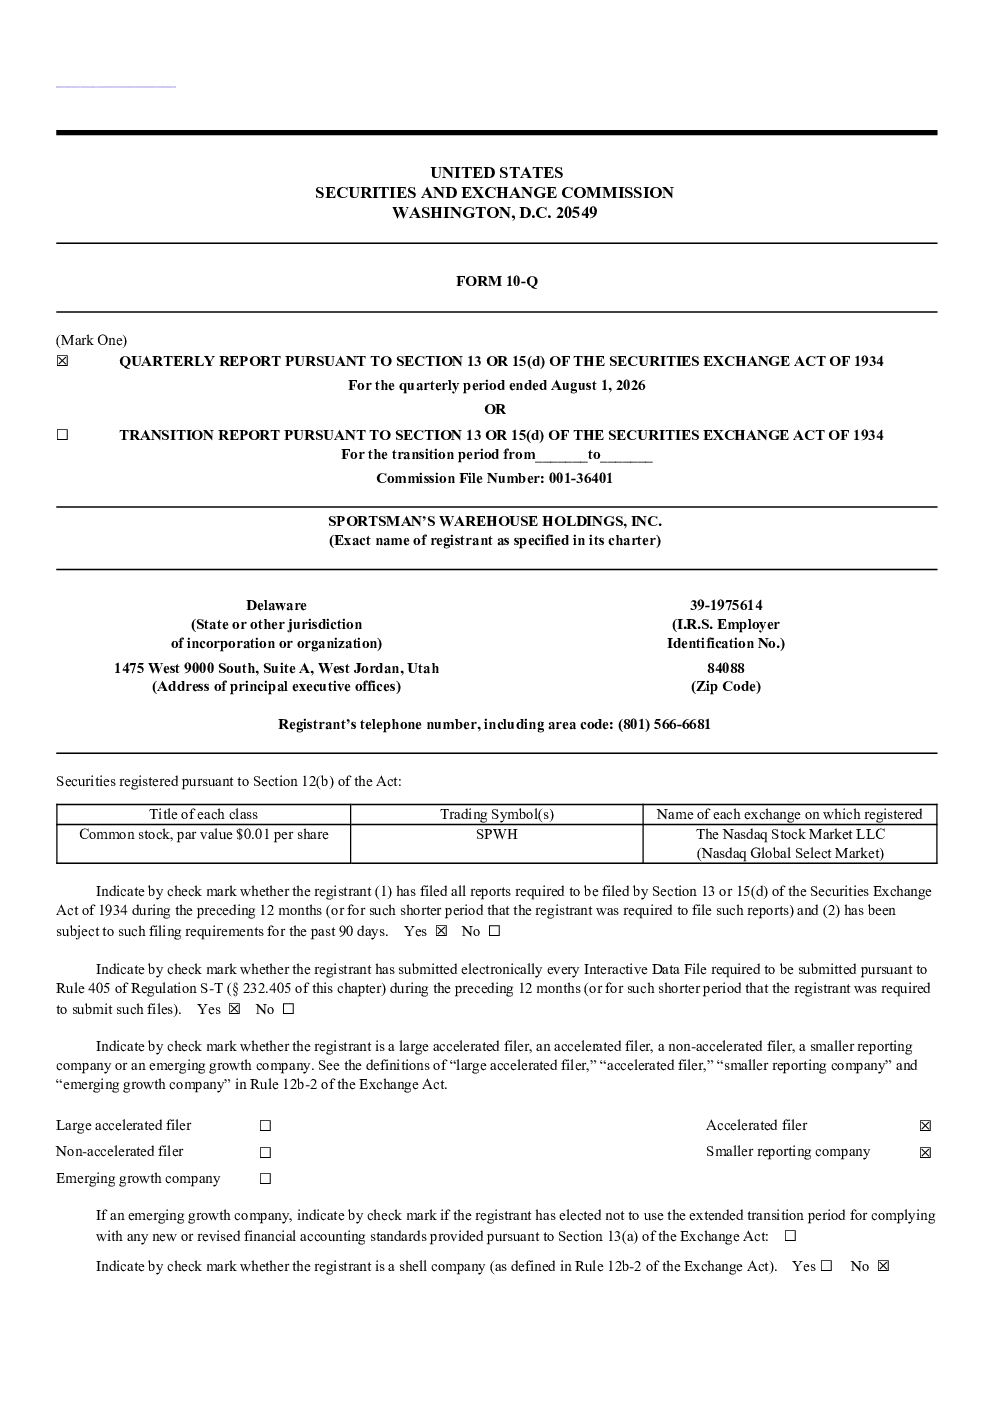
请勾选表示注册人(1)是否在过去的12个月(或注册人被要求提交此类报告的更短期间)已提交了《1934年证券交易法》第13条或第15(d)条要求提交的所有告,以及(2)在去90天内是否受到此提交要求。是 ☒ 否 请勾选表示注册人是否在过去的12个月(或注册人被要求提交此类文件的较短期间)内已通过电子方式提交了所有根据《S-T条例》第405条(本章§ 232.405)要求提交的交互式数据文件。是 ☒ 否 请勾选表明注册人是否为大型加速申报公司、加速申报公司、非加速申报公司、小型报告公司或成长型新兴公司。参见《交易所法案》第12b-2条中“大型加速申报公司”、“加速申报公司”、“小型报告公司”和“成长型新兴公司”的定义。 若为成长型新兴公司,请勾选表明注册人已选择不使用根据《交易所法案》第13(a)条提供的任何新或修订的财务会计准则的延期过渡期:☐ 请勾选表示注册人是否为空壳公司(根据交易所法案第12b-2条的定义)。是 ☐ 否 ☒ 体育用品仓储控股公司 目录 第一部分 财务信息 第一项。财务报表(未经审计):4 简明合并资产负债表 我们采用财政年度历法,在给定的财政年度中,由52或53周的周期构成,该周期结束于距离1月31日最近的周六。2026财年和2025财年的第二个财政季度分别于2026年8月1日和2025年8月2日结束。这两个季度均包含13周,分别称为2026财年第二季度和2025财年第二季度。2026财年包含52周运营时间,将于2027年1月30日结束。2025财年包含52周运营时间,已于2026年1月31日结束。 本文件中所有提及“Sportsman’s Warehouse”、“我们”、“我们”和“我们的”均指Sportsman’s Warehouse Holdings, Inc.及其子公司。所有提及“Holdings”的均指Sportsman’s Warehouse Holdings, Inc.,不包括其子公司。其中,(i)“2026财年”指截至2027年1月30日的财年;(ii)“2025财年”指截至2026年1月31日的财年。 关于前瞻性陈述的特殊说明 本10-Q季度报告(以下简称“10-Q”)包含构成前瞻性陈述的声明,该定义由1995年《私募证券诉讼改革法》规定。这些声明涉及我们的业务、运营和财务表现及状况,以及我们针对业务运营和财务表现及状况的计划、目标和预期,这些均受风险和不确定性的影响。本10-Q中除历史事实陈述外的所有陈述均为前瞻性陈述。这些声明可能包括“旨在”、“预期”、“假设”、“相信”、“可能拥有”、“可以”、“由于”、“估计”、“预期”、“目标”、“打算”、“可能”、“可能”、“目标”、“计划”、“处于有利地位”、“潜在的”、“预测”、“应该”、“目标”、“将”、“会”等词语以及具有类似含义的其他词语和术语,用于讨论未来运营或财务表现的时间或性质或其他事件或趋势。例如,我们所有关于未来运营、增长或举措和战略的计划和目标的声明均为前瞻性陈述。 这些前瞻性陈述基于对我们业务以及我们所处行业当前的预期、估计、预测和展望,以及我们管理层信念和假设。我们许多前瞻性陈述源自我们自身的经营预算和预测,这些预算和预测基于许多详细假设。虽然我们相信我们的假设是合理的,但我们提醒说,预测已知因素的影响非常困难,我们无法预见所有可能影响我们实际结果的因素。 我们所有前瞻性陈述均受风险和不确定性的影响,这些风险和不确定性可能导致我们的实际结果与我们的预期产生重大差异。可能导致实际结果与预期产生重大差异的重要因素包括但不限于: • 当前及未来的政府法规,特别是涉及枪支弹药销售的规定,可能对产品的需求以及我们开展业务的能力产生负面影响;• 以零售为基础的业务模式,受宏观经济和市场条件影响,如利率上升、通货膨胀压力以及经济、市场及金融不确定性,可能导致消费者支出下降; • 店铺集中于美国西部,使我们易受该地区不利条件的影响,并可能影响我们的销售额,导致经营业绩受损; • 我们所处的高度分散且竞争激烈的行业,以及竞争加剧的可能性; • 消费者需求的变化,包括地区偏好,而我们可能无法及时识别和应对这些变化; • 进入新市场或现有市场的新业务,包括我们未来期间开设新店的长期战略,这可能不成功; • 关闭表现不佳店铺的成本,如果我们决定这样做,这些成本可能很大; • 与数据隐私和安全相关的严格且不断变化的美国义务;以及 • 总体宏观经济状况的影响,如劳动力短缺、通货膨胀、利率上升、关税和贸易争端的影响、经济放缓、衰退或市场调整。 以上并非导致实际结果与我们的预期产生差异的所有因素或事件的完整清单,我们无法预测所有这些因素。所有可归因于我们或代表我们行动的人的书面和口头前瞻性陈述,均以其全文中“第一部分”下披露的谨慎陈述为限。 3第一项A,“风险因素”,见我们截至2026年1月31日财政年度终了的10-K表格年度报告(以下简称“财政2025年10-K报告”),以及本10-Q报告中的“第一部分,第二项,管理层对财务状况和经营成果的分析”等处;此类披露可能随时被我们向证券交易委员会(“SEC”)提交的其他报告,包括后续的10-K表格年度报告和10-Q表格季度报告以及公开信息进行修改、补充或取代。您应结合这些风险和不确定性,评估本10-Q报告及 Context of the context of the context of the context of the context of the context ofthe context of the context of the context of the context of the context of the context of the context of the contextof the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of thecontext of the context of the context of the context of the context of the context of the context of the context ofthe context of the context of the context of the context of the context of the context of the context of the contextof the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of thecontext of the context of the context of the context of the context of the context of the context of the context ofthe context of the context of the context of the context of the context of the context of the context of the contextof the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of thecontext of the context of the context of the context of the context of the context of the context of the context ofthe context of the context of the context of the context of the context of the context of the context of the contextof the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of the context of thecontext of the context of the context of the context of the context of the context of the context of the context ofthe context of投资者及其他读者在评估我们的前瞻性陈述时,应仔细考虑这些因素,并注意不要过度依赖我们所作的任何前瞻性陈述。这些前瞻性陈述仅就本10-Q报告日的日期而言,并非对未来业绩或发展的保证,且涉及已知和未知风险、不确定性及其他在许多情况下超出我们控制的因素。除非法律规定,否则我们无义务公开更新或修订任何前瞻性陈述,无论是由新信息、未来发展或其他原因导致。 运动品仓储控股公司及其子公司合并资产负债表(未经审计)金额单位:千元,除面值外 运动员仓库控股公司及其子公司的合并股东权益简化报表金额单位:千元(未经审计) 体育用品仓储控股公司 以及子公司 合并简要财务报表注释 美元单位为千美元,每股金额除外(未经审计) (1) 公司业务说明及报告基础 业务描述 体育用品仓库控股公司(以下简称“控股公司”)及其子公司(统称“公司”)经营体育用品零售店。截至2026年8月1日,公司在美国32个州经营147家门店。公司还在sportsmans.com网站运营电子商务平台。公司的门店和网站被合并为一个经营和报告单元。 汇报基础 此处所包含的合并财务报表未经审计,由公司管理层根据美国证券交易委员会(“SEC”)的规则和法规编制而成。根据此类规则和法规,某些通常包含在美国公认会计原则(“GAAP”)编制的财务报表中的信息和脚注披露已被简化或省略。公司截至2026年1月31日的合并资产负债表源自该公司截至该日期的经审计合并资产负债表。此处包含的所有其他合并财务报表均未经审计,并反映了管理层认为为公平总结所列期间公司合并财务报表所必需的所有调整。所有这些调整均为正常重复性性质。截至2026年8月1日财季的结果不一定能反映截至2027年1月30日财年可获得的结果。应结合公司提交给SEC的、截至2026年1月31日财年10-K表格年度报告(“2025财年10-K表格”)中包含的经审计合并财务报表及其注释,来阅读此处所包含的合并财务报表。