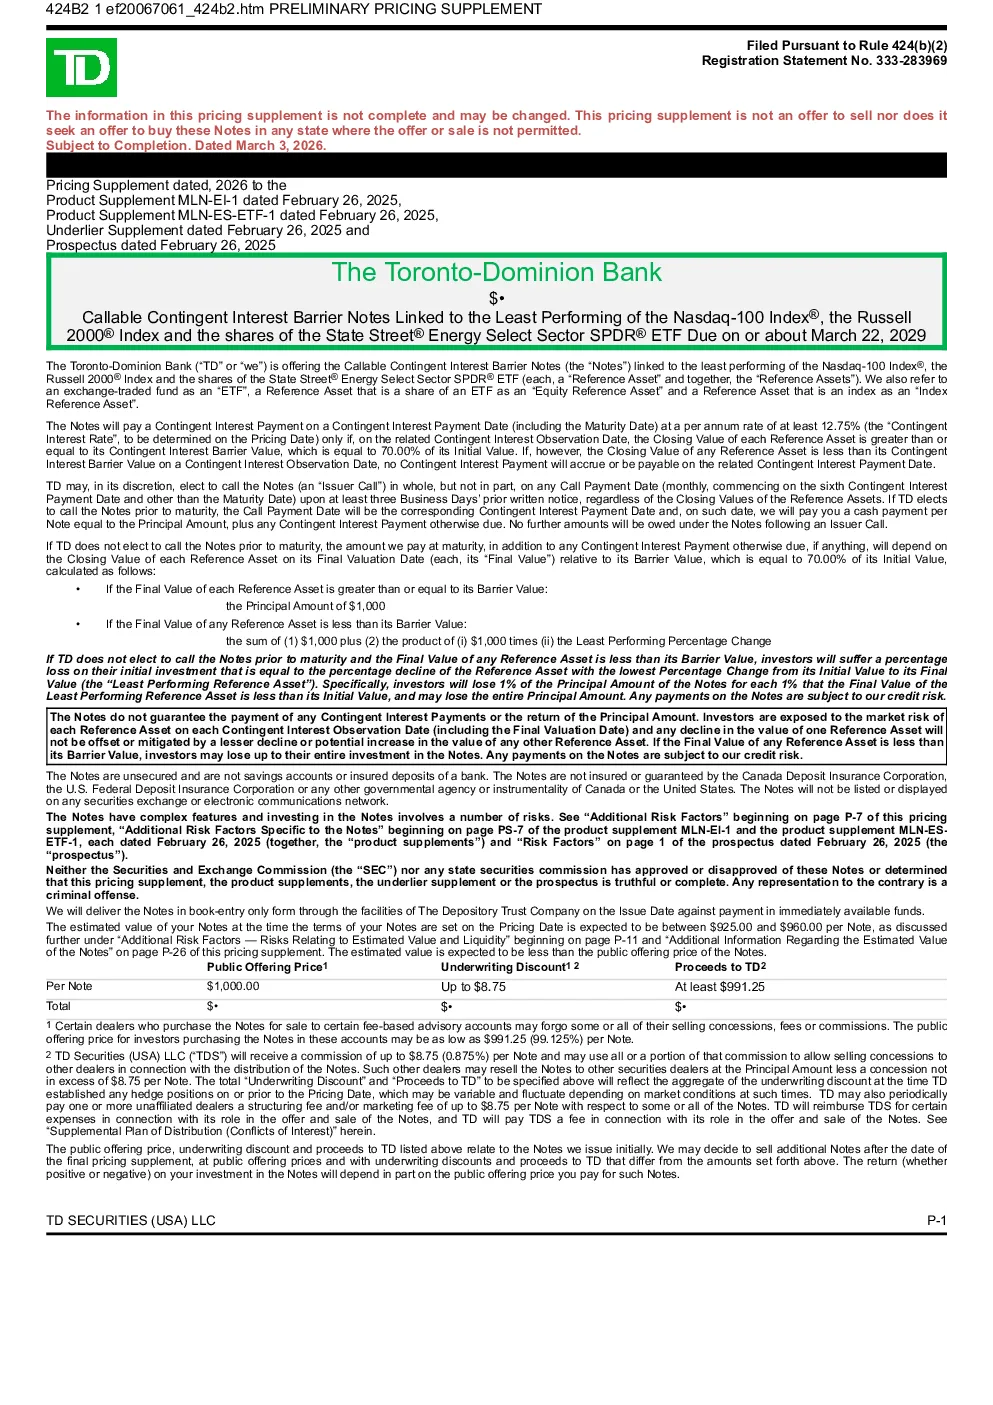
The Toronto-Dominion Bank is offering Callable Contingent Interest Barrier Notes linked to the least performing of the Nasdaq-100 Index®, the Russell 2000®Index, and the shares of the State Street®Energy Select Sector SPDR®ETF. The Notes will pay a Contingent Interest Payment at a rate of at least 12.75% per annum only if the Closing Value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value (70.00% of its Initial Value) on the related Contingent Interest Observation Date. If the Closing Value of any Reference Asset is less than its Contingent Interest Barrier Value on a Contingent Interest Observation Date, no Contingent Interest Payment will accrue or be payable.
Key features and risks:
- Callable Feature: TD may call the Notes in whole on any Call Payment Date (monthly, commencing on the sixth Contingent Interest Payment Date) upon at least three Business Days’ prior written notice, regardless of the Closing Values of the Reference Assets.
- Return Structure: If TD does not call the Notes prior to maturity, the payment at maturity will be:
- $1,000 if the Final Value of each Reference Asset is greater than or equal to its Barrier Value.
- The sum of $1,000 plus the product of $1,000 times the Least Performing Percentage Change if the Final Value of any Reference Asset is less than its Barrier Value.
- Risk of Loss: Investors may lose up to their entire investment if the Final Value of any Reference Asset is less than its Barrier Value.
- Market Risk: Investors are exposed to the market risk of each Reference Asset on each Contingent Interest Observation Date.
- Liquidity Risk: The Notes are not insured or guaranteed and may not be listed or displayed on any securities exchange or electronic communications network, potentially leading to limited liquidity and significant losses in the secondary market.
- Taxation: The U.S. tax treatment of the Notes is uncertain, and potential conflicts of interest exist due to TD’s role as the Calculation Agent and its other trading activities.
The estimated value of the Notes at the time the terms are set on the Pricing Date is expected to be between $925.00 and $960.00 per Note, which is less than the public offering price. The estimated value is based on TD’s internal funding rate and pricing models, which may differ from other financial institutions’ models.