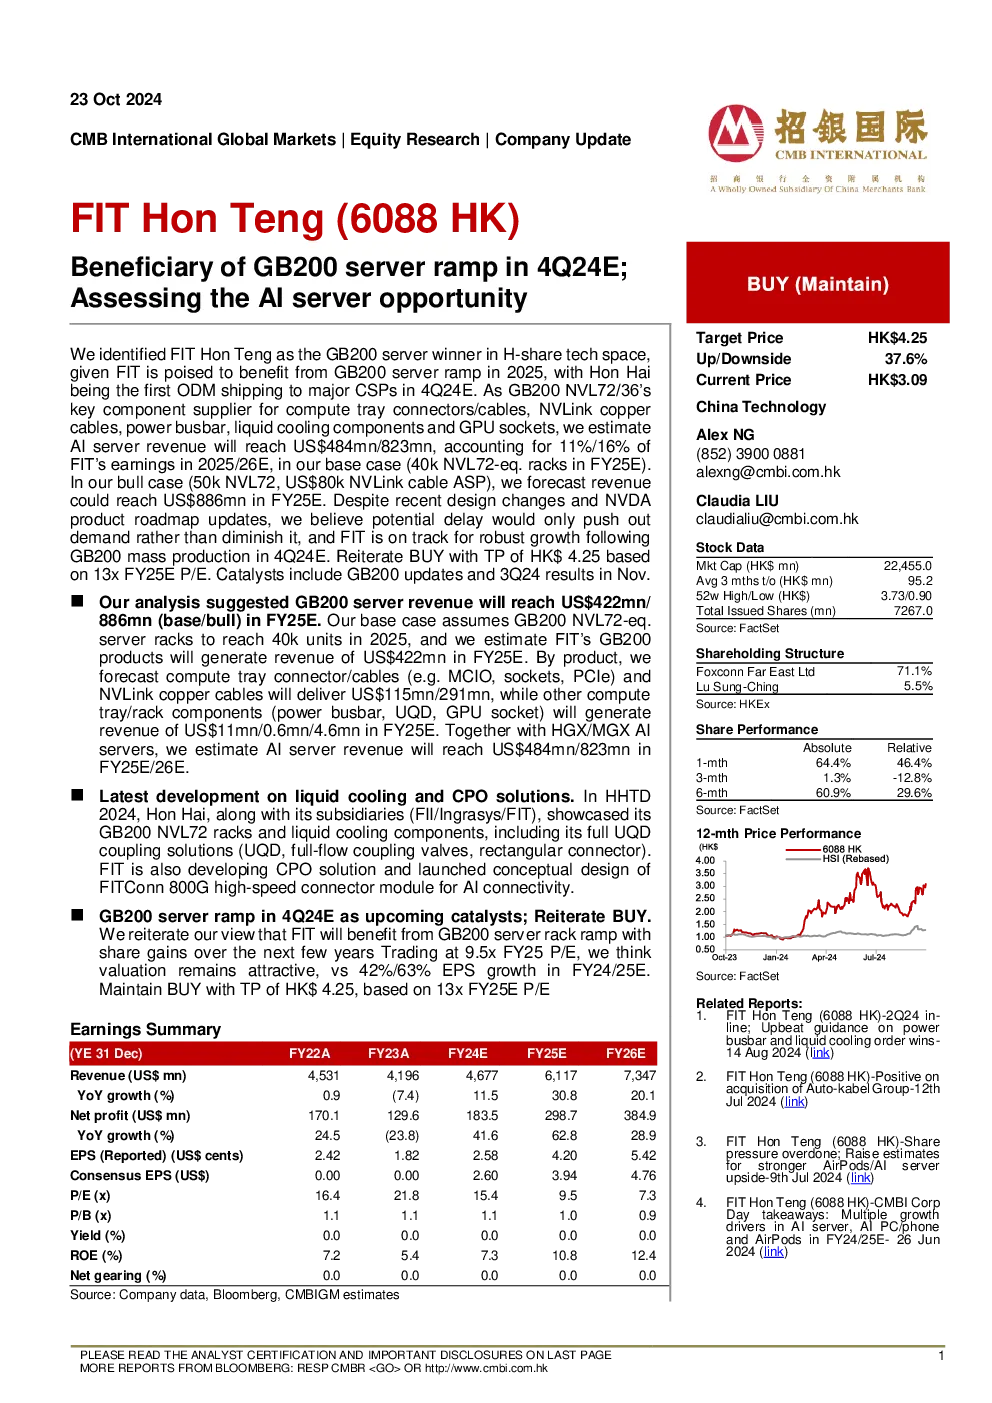
FIT Hon Teng (6088 HK): AI Server Opportunity and Financial Projections
Key Highlights:
- GB200 Server Ramp: FIT Hon Teng is positioned to benefit significantly from the GB200 server ramp starting in the fourth quarter of 2024.
- Revenue Projections:
- Base Case: FIT is expected to generate AI server revenue of $484 million in fiscal year 2025, accounting for 11% of its earnings.
- Bull Case: Under a more optimistic scenario, revenue could reach $886 million in fiscal year 2025.
- Product Breakdown:
- Compute Tray Connectors/Cables: Expected to contribute $115 million in revenue.
- NVLink Copper Cables: Estimated to bring in $291 million in revenue.
- Other Compute Tray/Rack Components: Including power busbars, generating $11 million in revenue.
- GPU Sockets: Projected to add $4.6 million in revenue.
Financial Estimates:
- EPS Growth: FIT is expected to see significant EPS growth, with projected increases of 62.8% in fiscal year 2025.
- P/E Ratio: Currently trading at 9.5x FY25E P/E, making it undervalued relative to its earnings growth potential.
- Valuation: Based on a 13x FY25E P/E, the target price is set at HK$4.25, representing a 37.6% upside from the current price of HK$3.09.
Recent Developments:
- Liquid Cooling and CPO Solutions: FIT is developing advanced liquid cooling components and CPO solutions, such as the FITConn 800G high-speed connector module.
- GB200 Server Ramp: Hon Hai, through its subsidiaries, is showcasing GB200 NVL72 racks and liquid cooling components at industry events like HHTD 2024.
Market Position:
- Competitive Advantage: FIT is well-positioned to capture market share in the AI server segment, benefiting from the growing demand for advanced computing solutions.
Analyst Recommendations:
- Reiterate BUY: Given the strong growth prospects and attractive valuation, the analyst maintains a BUY rating with a target price of HK$4.25.
Summary Table: FIT Hon Teng (6088 HK) - Key Metrics
| Metric | Fiscal Year 2025E | Fiscal Year 2026E |
|-----------------------|-----------------------|-----------------------|
| Revenue (US$ million) | $6,117 | $7,347 |
| Net Profit (US$ million) | $298.7 | $384.9 |
| EPS (US$ cents) | $4.20 | $5.42 |
| P/E Ratio | 9.5 | 7.3 |
| Target Price (HK$) | 4.25 | - |
Conclusion:
FIT Hon Teng is poised to capitalize on the growing AI server market, particularly with the GB200 server ramp. The company is expected to see significant revenue and earnings growth, supported by strong product offerings and competitive positioning. The current undervalued valuation makes it an attractive investment opportunity.