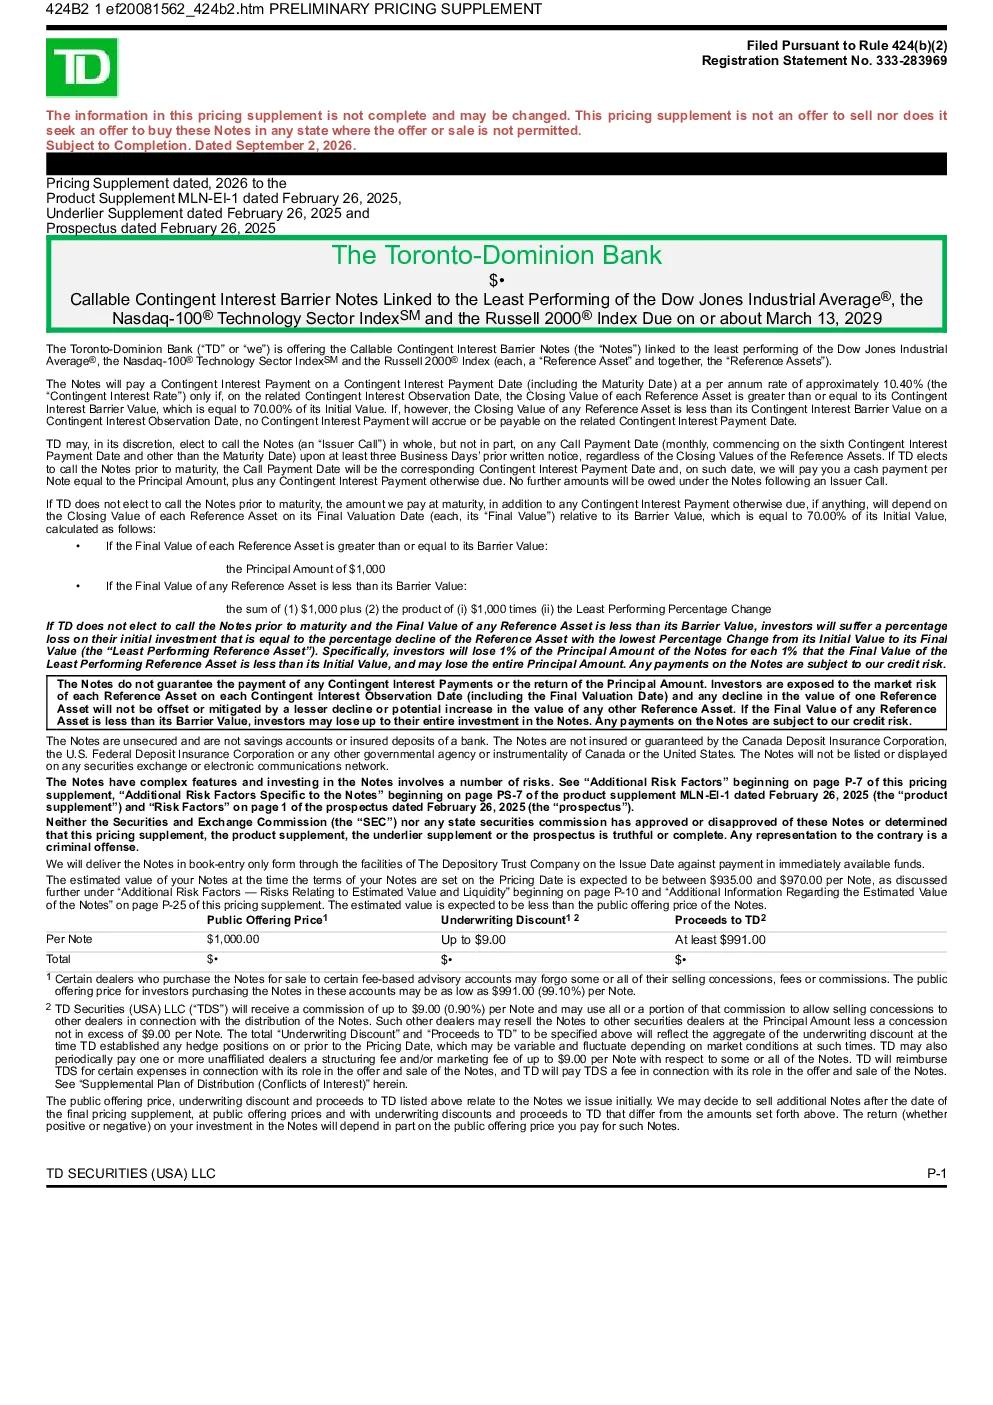
The Toronto-Dominion Bank (TD) is offering Callable Contingent Interest Barrier Notes linked to the least performing of the Dow Jones Industrial Average®, the Nasdaq-100®Technology Sector IndexSM, and the Russell 2000®Index. The Notes will pay a Contingent Interest Rate of approximately 10.40% per annum only if the Closing Value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value (70.00% of its Initial Value). If the Closing Value of any Reference Asset falls below its Barrier Value on a Contingent Interest Observation Date, no Contingent Interest Payment will be made.
Key Features and Risks:
- Callable Feature: TD may call the Notes in whole on any Call Payment Date (monthly, starting from the sixth Contingent Interest Payment Date) with at least three Business Days' notice, regardless of the Reference Assets' values. If called, investors will receive the Principal Amount plus any accrued Contingent Interest Payment.
- Contingent Interest and Principal Repayment: If TD does not call the Notes, the repayment at maturity will depend on the Final Value of each Reference Asset relative to its Barrier Value (also 70.00% of its Initial Value):
- If all Final Values are greater than or equal to their Barrier Values, investors receive $1,000 principal.
- If any Final Value is less than its Barrier Value, investors receive $1,000 plus the product of $1,000 and the Least Performing Percentage Change, resulting in potential losses.
- Risks:
- Return Risk: The Notes do not guarantee principal repayment or Contingent Interest Payments. Investors may lose their entire investment if the least performing Reference Asset's Final Value is below its Barrier Value.
- Market Risk: Investors are exposed to the market risks of each Reference Asset on each Contingent Interest Observation Date. Poor performance of any single asset will negatively impact returns.
- Liquidity Risk: The Notes are unsecured and not listed, potentially leading to limited liquidity and significant losses if sold in the secondary market before maturity.
- Interest Rate Risk: The Notes are more sensitive to interest rate fluctuations due to the contingent interest and issuer call features.
- Credit Risk: Payments on the Notes are subject to TD's credit risk.
- Taxation Risk: The U.S. tax treatment of the Notes is uncertain, potentially impacting investors' tax liabilities.
Estimated Value and Pricing:
- The estimated value of the Notes at the Pricing Date is expected to be between $935.00 and $970.00 per Note, lower than the public offering price.
- The estimated value is based on TD's internal funding rate and pricing models, which may differ from other financial institutions' models.
- The public offering price includes an underwriting discount and proceeds to TD, which may fluctuate based on market conditions.
Additional Information:
- The Notes are linked to the least performing of the three Reference Assets, increasing the risk of no Contingent Interest Payments and potential losses.
- The Notes are subject to risks associated with the technology sector and small-cap companies, as represented by the Nasdaq-100®Technology Sector IndexSM and the Russell 2000®Index, respectively.
- TD may engage in hedging activities, which could create conflicts of interest and impact the Notes' market value.
- The Notes do not guarantee the payment of any Contingent Interest Payments or the return of the Principal Amount.
- Investors are advised to consult their investment, legal, tax, and accounting advisors before investing in the Notes.