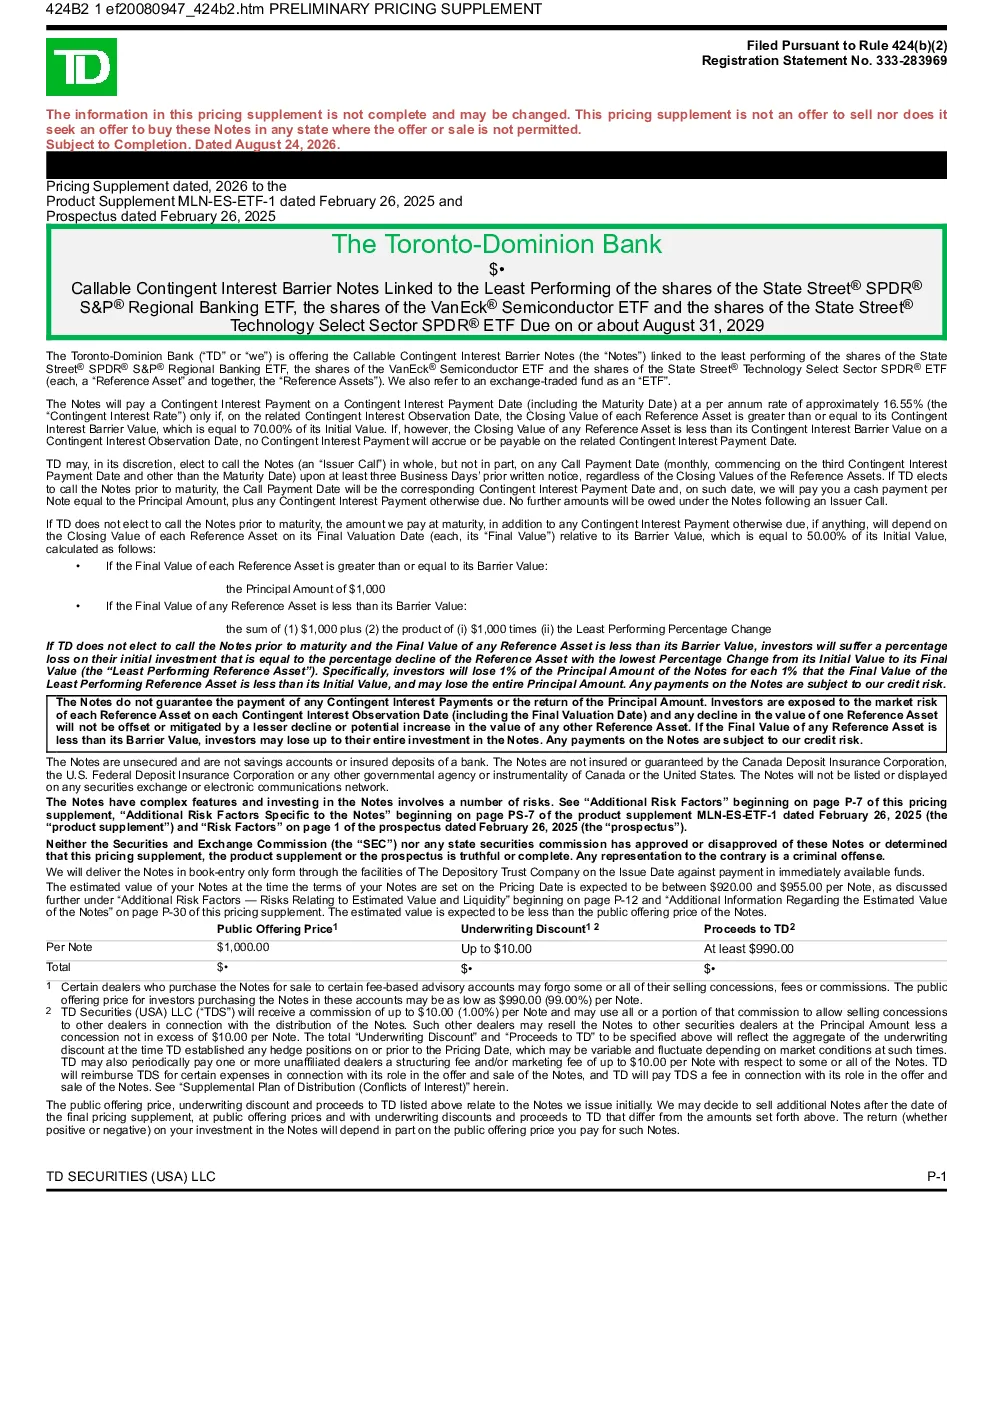
The Toronto-Dominion Bank is offering Callable Contingent Interest Barrier Notes linked to the least performing of three reference assets: the State Street®SPDR®S&P®Regional Banking ETF (KRE Fund), the VanEck®Semiconductor ETF (SMH Fund), and the State Street®Technology Select Sector SPDR®ETF (XLK Fund). The Notes will pay a Contingent Interest Payment at a rate of approximately 16.55% per annum only if the Closing Value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value (70.00% of its Initial Value) on the related Contingent Interest Observation Date. If the Closing Value of any Reference Asset is less than its Contingent Interest Barrier Value on a Contingent Interest Observation Date, no Contingent Interest Payment will be paid.
Key Features and Risks:
- Callable Feature: TD may elect to call the Notes in whole on any Call Payment Date (monthly, commencing on the third Contingent Interest Payment Date) upon at least three Business Days’ prior written notice, regardless of the Closing Values of the Reference Assets. If called, investors will receive the Principal Amount plus any Contingent Interest Payment otherwise due.
- Contingent Interest Payment: The Notes will pay a Contingent Interest Payment only if the Closing Value of each Reference Asset is greater than or equal to its Contingent Interest Barrier Value. If the Closing Value of any Reference Asset is less than its Contingent Interest Barrier Value on a Contingent Interest Observation Date, no Contingent Interest Payment will accrue or be payable on the related Contingent Interest Payment Date.
- Maturity Payment: If TD does not elect to call the Notes prior to maturity, the amount paid at maturity will depend on the Final Value of each Reference Asset on its Final Valuation Date relative to its Barrier Value (50.00% of its Initial Value):
- If the Final Value of each Reference Asset is greater than or equal to its Barrier Value, investors will receive the Principal Amount of $1,000.
- If the Final Value of any Reference Asset is less than its Barrier Value, investors will receive the Principal Amount plus the product of $1,000 times the Least Performing Percentage Change.
- Risks: Investors are exposed to various risks, including:
- Market Risk: The value of the Notes is contingent upon the performance of the Reference Assets. A decline in the value of one Reference Asset will not be offset by a lesser decline or potential increase in the value of any other Reference Asset.
- Credit Risk: The payment of any amount due on the Notes is subject to TD’s credit risk.
- Liquidity Risk: The Notes are unsecured and not insured or guaranteed by any governmental agency. There may be little or no secondary market for the Notes, and the estimated value is expected to be less than the public offering price.
- Interest Rate Risk: The Notes may be more sensitive to fluctuations in interest rates due to the contingent interest and Issuer Call features.
- Taxation Risk: The U.S. tax treatment of the Notes is uncertain, and investors should consult their tax advisors.
Examples of Potential Outcomes:
- Example 1: If TD calls the Notes on the first potential Call Payment Date and the Closing Value of at least one Reference Asset is less than its Contingent Interest Barrier Value on the corresponding Contingent Interest Observation Date, investors will receive $1,000 per Note, representing a total return of 2.7584%.
- Example 2: If TD does not elect to call the Notes prior to maturity and the Final Value of each Reference Asset is greater than or equal to its Barrier Value and Contingent Interest Barrier Value, investors will receive $1,013.792 per Note, representing a total return of 1.3792%.
- Example 3: If TD does not elect to call the Notes prior to maturity and the Final Value of each Reference Asset is greater than or equal to its Barrier Value but the Final Value of at least one Reference Asset is less than its Contingent Interest Barrier Value, investors will receive $1,000 per Note, representing a total return of 0.00%.
- Example 4: If TD does not elect to call the Notes prior to maturity and the Final Value of at least one Reference Asset is less than its Contingent Interest Barrier Value and Barrier Value, investors will receive $400 per Note, representing a loss of 60.00%.
Conclusion:
Investors should carefully consider the risks associated with the Notes, particularly the market risk of the Reference Assets, the potential for loss of principal, and the uncertainty of the U.S. tax treatment. The Notes are complex instruments with limited liquidity and potential for significant losses. Investors should consult their investment, legal, tax, and accounting advisors before investing.