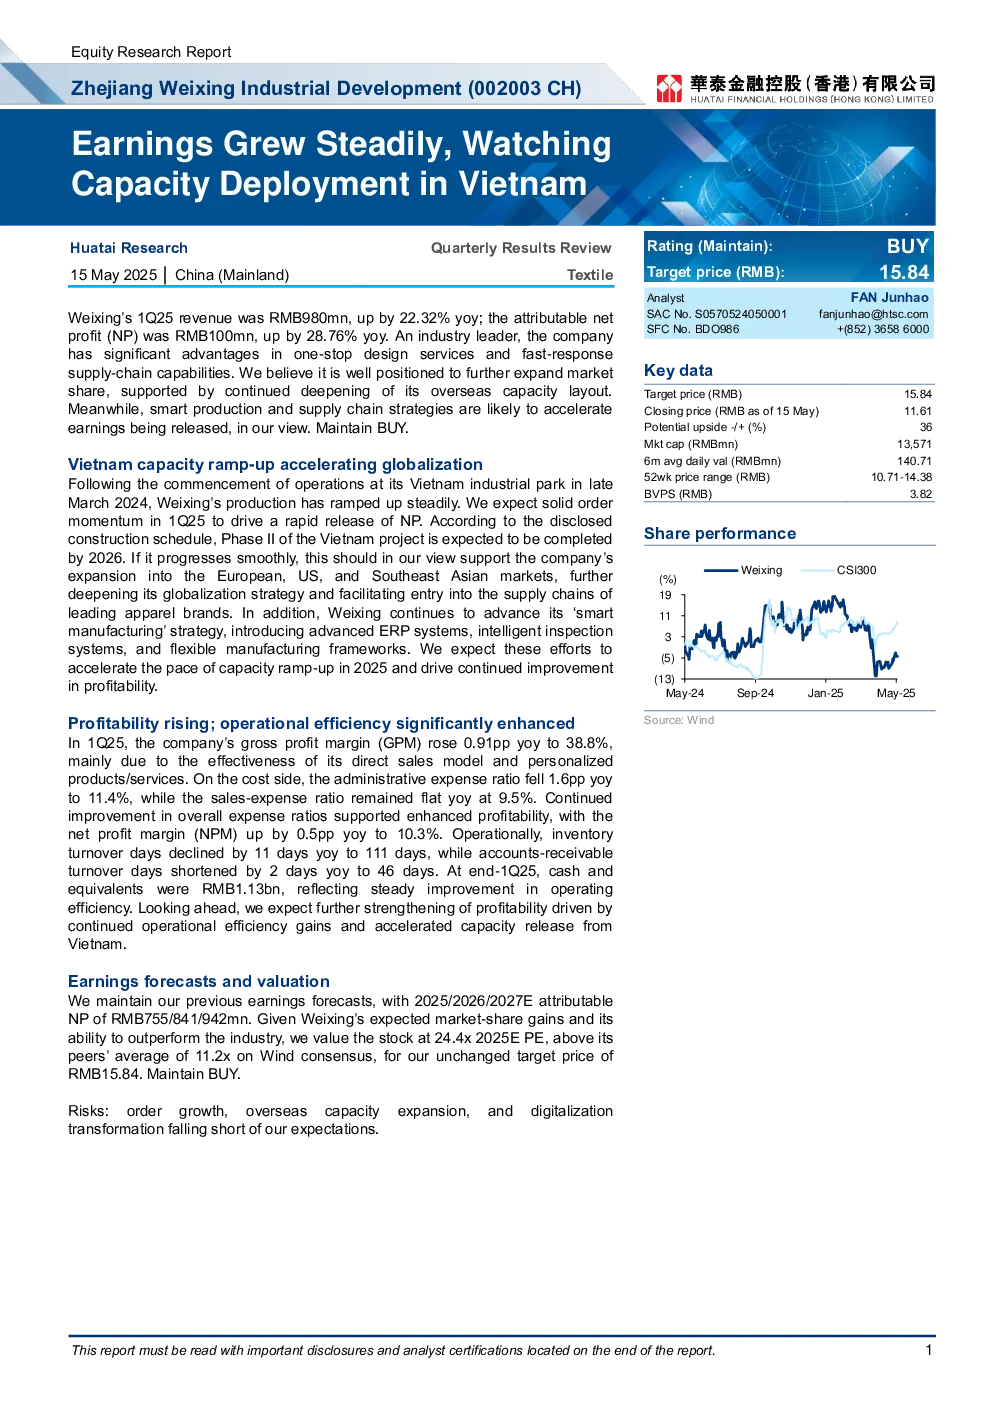
Weixing's 1Q25 revenue grew by 22.32% yoy to RMB980mn, with attributable net profit (NP) up by 28.76% yoy to RMB100mn. The company maintains significant advantages in one-stop design services and fast-response supply chain capabilities, positioning it well for further market share expansion supported by its overseas capacity layout. Key highlights include:
- Vietnam capacity ramp-up: Operations at the Vietnam industrial park commenced in late March 2024, with steady production growth expected to drive NP release. Phase II of the Vietnam project is scheduled for completion by 2026, supporting expansion into European, US, and Southeast Asian markets.
- Profitability and operational efficiency: Gross profit margin (GPM) rose 0.91pp yoy to 38.8%, driven by direct sales and personalized services. Administrative expense ratio fell 1.6pp yoy to 11.4%, while sales-expense ratio remained flat at 9.5%. Net profit margin (NPM) improved by 0.5pp yoy to 10.3%. Inventory turnover days decreased by 11 days to 111 days, and accounts-receivable turnover days shortened by 2 days to 46 days. Cash and equivalents reached RMB1.13bn at end-1Q25.
- Smart manufacturing strategy: The company continues to advance its 'smart manufacturing' initiatives, including advanced ERP systems, intelligent inspection systems, and flexible manufacturing frameworks, which are expected to accelerate capacity ramp-up and improve profitability.
- Earnings forecasts and valuation: The analyst maintains previous earnings forecasts with 2025/2026/2027E attributable NP of RMB755/841/942mn. The stock is valued at 24.4x 2025E PE, above the peer average of 11.2x, supporting an unchanged target price of RMB15.84. The rating is maintained at BUY.
- Risks: Key risks include order growth, overseas capacity expansion, and digitalization transformation falling short of expectations.
Financials and detailed disclosures are provided in the full report.