Xtep Company Update: Navigating Macro Challenges
Executive Summary:
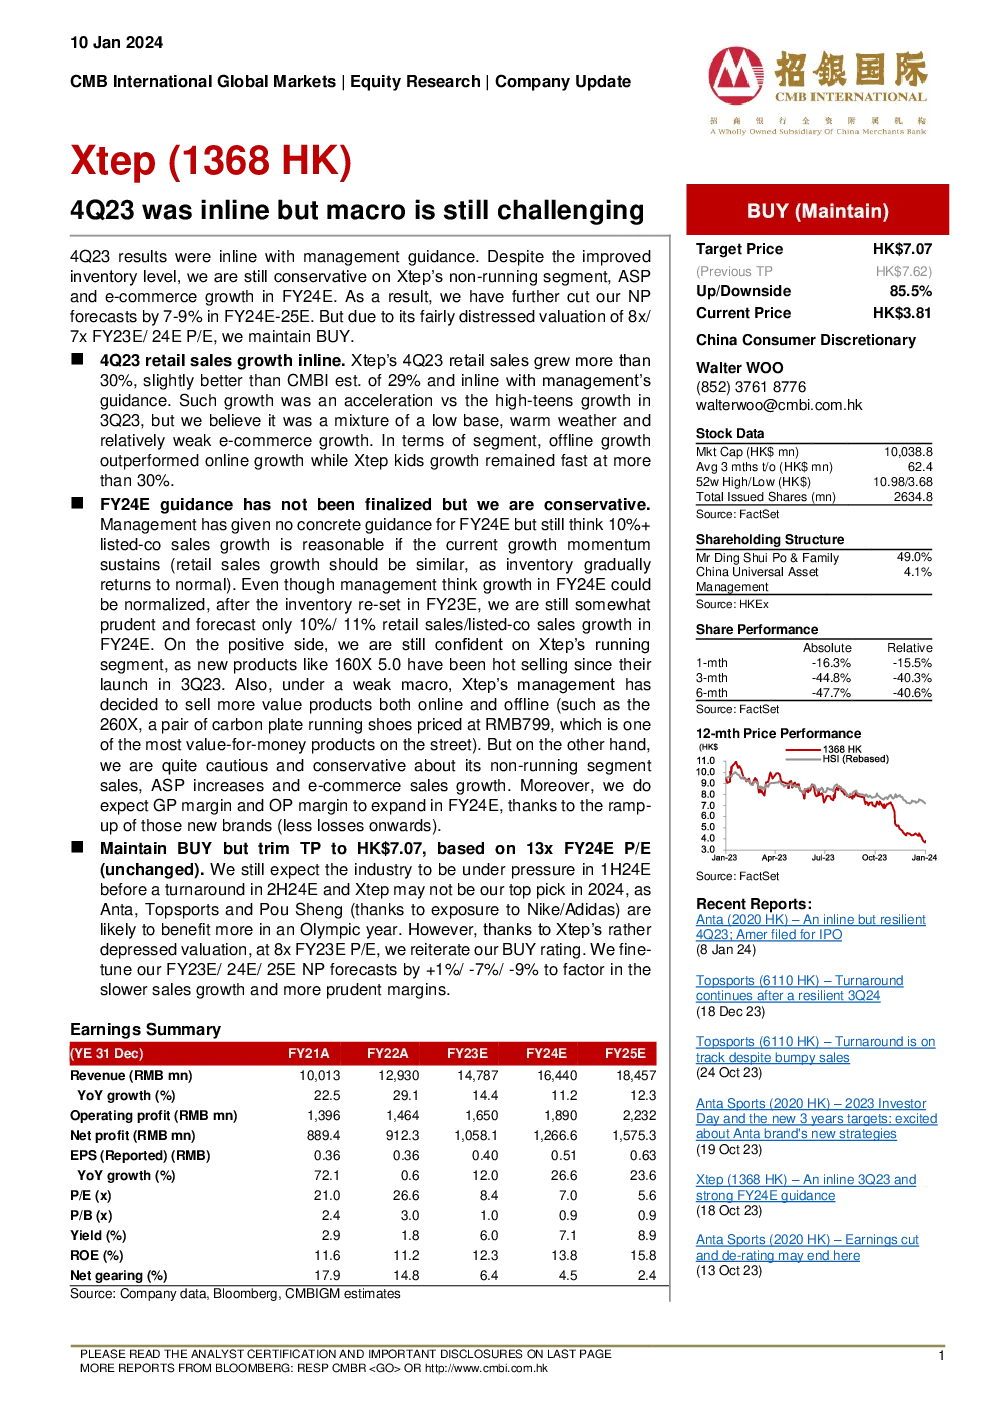
Xtep, a leading Chinese sportswear company, reported 4Q23 results that were in line with expectations, marking an acceleration from the high-teens growth seen in 3Q23. However, the company faces challenges in its non-running segment, ASP increases, and e-commerce growth, prompting a cut in net profit forecasts by 7-9% for FY24E-25E. Despite this, Xtep's stock retains a "BUY" rating due to its depressed valuation and potential for GP margin expansion.
Key Financial Highlights:
- Revenue: FY23 saw a revenue increase of 14.4% to 14,787 million RMB, projecting growth to 16,440 million RMB in FY24E and 18,457 million RMB in FY25E.
- Net Profit: Net profit for FY23 reached 1,058.1 million RMB, expecting a further rise to 1,266.6 million RMB in FY24E and 1,575.3 million RMB in FY25E.
- Valuation: The stock trades at 8x FY23E P/E, offering a compelling investment opportunity.
Operational Performance:
- Retail Sales Growth: 4Q23 retail sales growth was more than 30%, exceeding management's guidance, attributed to a mix of a low base, warmer weather conditions, and relatively weak e-commerce growth.
- Inventory Management: Inventory levels have returned to a favorable level, with the inventory to retail sales ratio at 4 to 4.5 months, improving from 4.5 to 5 months in 3Q23. This indicates effective inventory clearance strategies.
- Brand Performance: The running segment shows strong performance with new product launches like the 160X 5.0 series. In contrast, the non-running segment faces cautious outlooks regarding sales, ASP increases, and e-commerce growth.
Outlook and Strategy:
- Guidance for FY24E: Management remains optimistic, expecting 10%+ listed-co sales growth, assuming the current growth momentum sustains. However, the report adopts a more conservative stance, forecasting only 10%/11% retail sales/listed-co sales growth in FY24E.
- New Brand Strategy: Xtep aims to sell more value products both online and offline, exemplified by the 260X, a carbon plate running shoe priced at RMB799, highlighting the brand's commitment to affordability and market adaptability.
Valuation and Rating:
- Target Price: The target price has been adjusted to HK$7.07, based on a 13x FY24E P/E, maintaining the "BUY" rating despite the cut in forecasts.
- Market Positioning: Xtep may not be the top pick in 2024 due to competitors' potential benefits from the Olympic year and stronger exposure to global brands like Nike and Adidas. However, the stock's depressed valuation makes it attractive for investors seeking undervalued opportunities.
Conclusion:
Despite facing macroeconomic challenges and specific segmental hurdles, Xtep demonstrates resilience through strategic inventory management and targeted brand growth. The company's focus on value products and new brand development positions it well for future growth, supported by a favorable valuation.