猜你想问
Progressive集团9月财务表现如何?
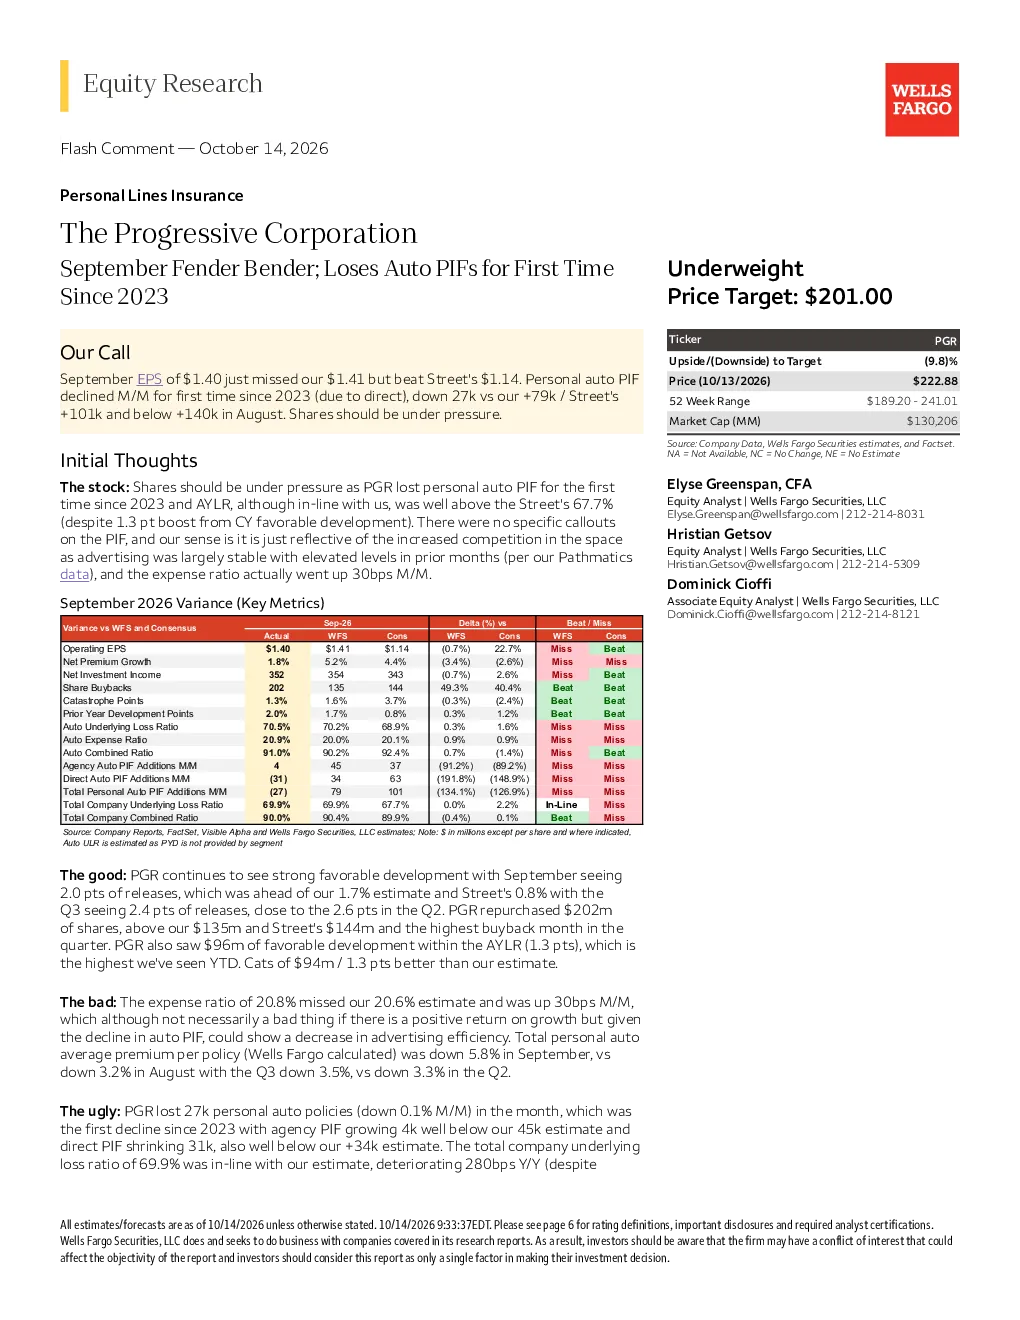
The Progressive Corporation (PGR) September EPS of $1.40 missed expectations slightly but beat Street estimates. Key metrics showed personal auto PIFs declining for the first time since 2023, driven by direct lines. The expense ratio increased by 30 bps M/M, and net premium growth slowed. Favorable development offset some deterioration, but the loss of 27k personal auto policies was notable.
个人Lines保险行业发展趋势如何?
The personal auto insurance market is experiencing a shift with direct lines driving policy growth. However, the recent decline in PIFs indicates potential challenges in maintaining growth momentum. The industry faces competition from new entrants and evolving customer preferences, requiring insurers to adapt their strategies to sustain profitability and market share.
报告重点分析了哪些方面?
The report focuses on Progressive's financial performance, particularly the decline in personal auto PIFs for the first time since 2023. It examines the impact of direct lines on policy growth, the increase in expense ratio, and the slowdown in net premium growth. Additionally, the report highlights the loss of 27k personal auto policies and its implications for the company's future growth prospects.
当前市场现状如何判断?
The current market for personal auto insurance is characterized by increasing competition and evolving customer behavior. Insurers are facing pressure to innovate and improve efficiency to maintain their market position. The recent trends indicate a need for companies to reassess their strategies and focus on customer retention and cost management to navigate the changing market dynamics.
研报提示了哪些风险?
The report identifies several risks associated with Progressive's business. These include the minimal impact from tariffs, potential for better-than-expected margins, and the possibility of higher-than-expected PIF growth. Additionally, the loss of 27k personal auto policies poses a risk to policy growth and profitability. These factors should be considered when evaluating the company's future performance.