转身
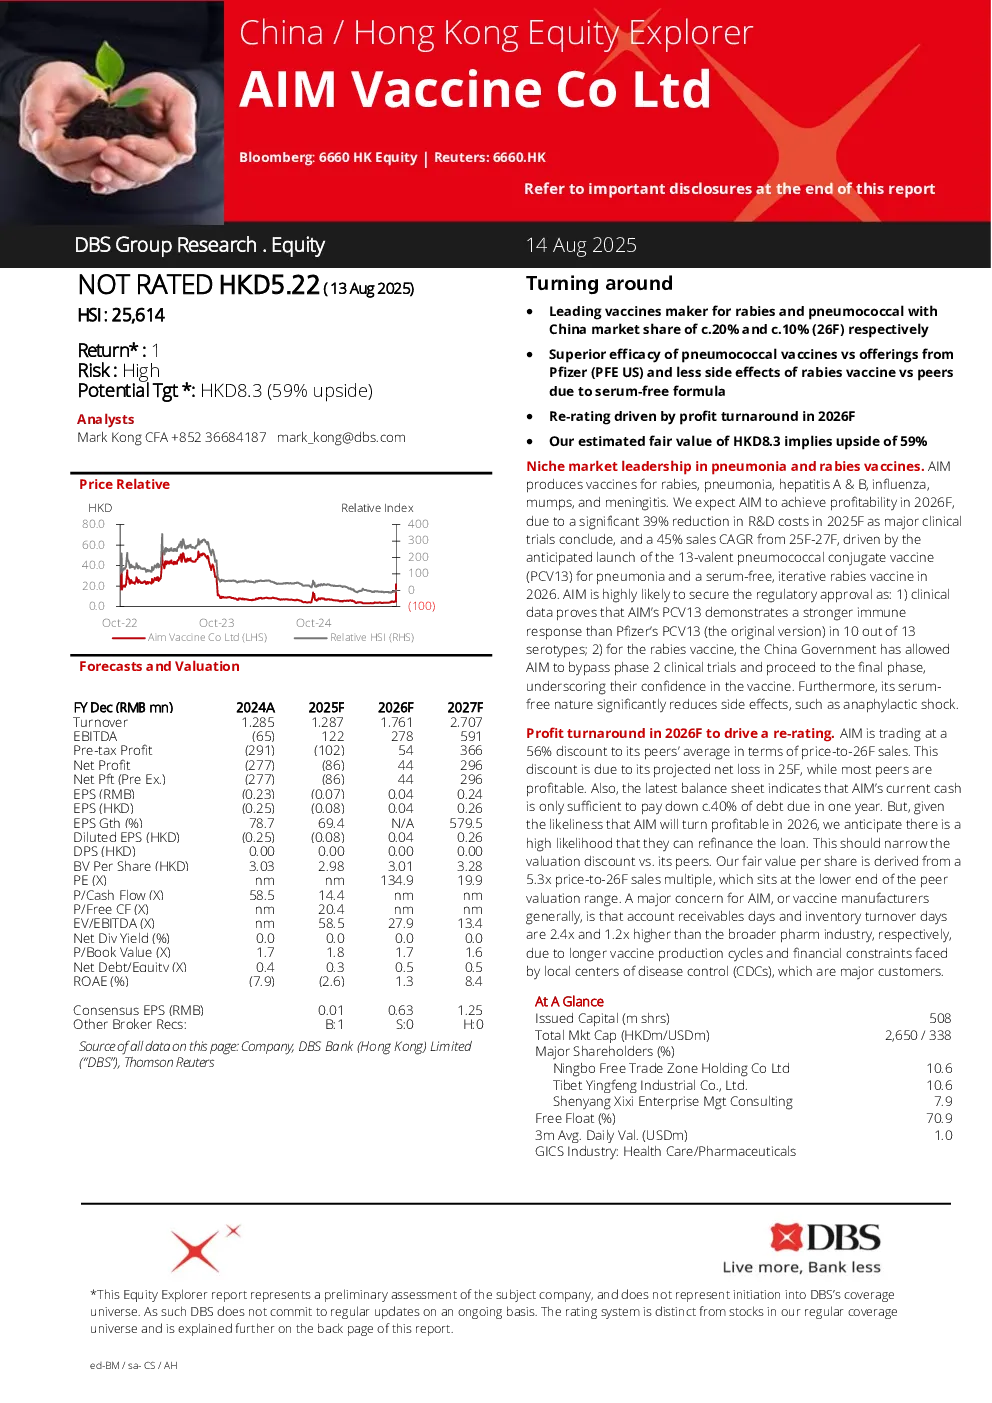
AIM Vaccine Co Ltd Bloomberg:6660 HK Equity|Reuters:6660.HK Refer to important disclosures at the end of this report DBS Group Research . Equity 14 Aug 2025 Turning around •Leadingvaccines maker forrabies andpneumococcalwithChinamarket share ofc.20%andc.10% (26F)respectively•Superior efficacy ofpneumococcalvaccines vs offerings fromPfizer (PFE US)andlessside effectsof rabies vaccinevs peersdue toserum-freeformula•Re-ratingdriven byprofit turnaroundin 2026F•Ourestimated fairvalueof HKD8.3implies upside of59% HSI:25,614 Return* : 1Risk : HighPotential Tgt *: HKD8.3 (59% upside) AnalystsMark Kong CFA +852 36684187mark_kong@dbs.com Nichemarket leadershipinpneumoniaand rabiesvaccines.AIM produces vaccinesforrabies, pneumonia,hepatitis A & B, influenza,mumps,andmeningitis. We expect AIMto achieveprofitabilityin 2026F,due toa significant39%reduction inR&D costsin 2025F as major clinicaltrials conclude,anda45% sales CAGRfrom25F-27F,driven bytheanticipatedlaunch ofthe13-valent pneumococcal conjugate vaccine(PCV13) for pneumonia andaserum-free,iterative rabies vaccine in2026.AIMis highly likely tosecuretheregulatoryapprovalas: 1) clinicaldata proves that AIM’s PCV13demonstratesastrongerimmuneresponsethan Pfizer’s PCV13 (theoriginalversion) in 10 out of 13serotypes; 2) for the rabies vaccine,theChinaGovernmenthasallowedAIM tobypassphase 2 clinical trialsand proceedto the final phase,underscoringtheir confidencein the vaccine.Furthermore, itsserum-free naturesignificantly reducesside effects,such asanaphylactic shock. Forecasts and Valuation Profit turnaroundin 2026Ftodrive are-rating.AIM is trading ata56% discount toitspeers’averagein terms of price-to-26F sales. Thisdiscount isdueto its projectednet loss in 25F,whilemost peers areprofitable. Also, the latest balance sheet indicates that AIM’s currentcashisonly sufficientto paydown c.40% of debt due inoneyear.But, giventhe likeliness thatAIMwillturn profitablein 2026, weanticipatethere is ahigh likelihood that they canrefinance theloan.This should narrow thevaluation discount vs.itspeers.Our fair valueper shareis derived froma5.3x price-to-26F salesmultiple, which sits at thelowerend ofthepeervaluation range.A major concern forAIM,or vaccinemanufacturersgenerally, isthataccount receivables days and inventoryturnoverdaysare2.4x and 1.2xhigher than the broaderpharm industry,respectively,due to longervaccineproductioncyclesandfinancial constraints facedby localcenters of disease control(CDCs), which are majorcustomers. At A GlanceIssued Capital (m shrs) 508Total Mkt Cap (HKDm/USDm)2,650 / 338Major Shareholders (%)Ningbo Free Trade Zone Holding Co Ltd10.6Tibet Yingfeng Industrial Co., Ltd.10.6Shenyang Xixi EnterpriseMgtConsulting7.9Free Float (%)70.93m Avg.Daily Val. (USDm)1.0GICS Industry: Health Care/Pharmaceuticals *This Equity Explorer report represents a preliminary assessment of the subject company, and does not represent initiation into DBS’s coverageuniverse. As such DBS does not commit to regular updates on an ongoing basis. The rating system is distinct from stocks in our regular coverageuniverse and is explained further on the back page of this report. ed-BM/ sa-CS /AH Equity Explorer BUSINESS INTRODUCTION preventingvarious diseases,including rabies, pneumonia,hepatitisA & B, influenza, mumps,andmeningitis.AIM’s key operatingassetsincludefour production plants located inNingbo (Zhejiangprovince), Dalian (Liaoning province),and Taizhou (Jiangsuprovince). Established in2015andlistedontheHongKong StockExchangein 2022,AIM is a vaccines developer and manufacturerheadquartered in Beijing, China. The company focuses on Products in clinicaltrials Equity Explorer Management profile EARNINGS DRIVERS serotypes,based on a head-to-head clinical trial (see thetable“PSV13–domestic products’comparison”). AIM incurredanet loss of Rmb277mnin 2024. We project thisnetloss to narrow by 69% to Rmb86mn in2025beforeturningprofitable in 2026F with earnings of Rmb44mn. Earnings are thenprojected togrow 5.8x to Rmb296mnin 2027F, driven by twomajorfactors: The total sales volume of PCV13 in China is c.14mninjections.The room for growth is huge,as we estimateonly less than half of infantsandchildren in China arevaccinated against streptococcus pneumoniae, based on“Insight and Info”(see:中国肺炎球菌疫苗行业现状深度分析与未来投资预测报告(2024-2031年)_观研报告网). 1)We project R&D expenses to drop by 39% to Rmb220mnin2025F andremain stable in 2026F and 2027F.This is mainlybecause all phase 3 clinical trialswould becompleted in 2025.Phase 3 trialsare typicallymore expensive than previousphases,as the patientenrolmentsize canbe over 100%larger. In terms ofmarket sharebysales volume, Walvax Bio(300142 CH), Shenzhen Kangtai (300601 H),andPfizerholdc.43%, c.29%-36%,andc.20%,respectively, withprices ranging betweenRmb600-700 per injection.CanSino (6185 HK) justreceivedapproval in 1H25 toenter this market. 2)Rapid revenue growthis projected for2026F & 27F (see thechart“Revenue breakdown”), driven by